After The Storm: How Flood Insurance Supports Your Rebuild
August 17, 2025

When floodwaters recede, the real work begins—making your home safe, livable, and code-compliant again. Flood insurance is designed to fund that recovery, from debris removal and drying to rebuilding and even certain mitigation upgrades. Below is what coverage typically provides, how the claims process works, and how to use your policy wisely so you can rebuild stronger.


What Flood Insurance Typically Covers After a Flood

Flood insurance (such as an NFIP policy sold through participating insurers) can help pay for:

  • Structural repairs: Damage to walls, floors, built-ins, and other parts of the insured building (up to your building coverage limit).

  • Personal property: Furniture, clothing, appliances, and other belongings inside the home (up to your contents limit). Coverage is usually on actual cash value (ACV) for contents; some building items may qualify for replacement cost if eligibility criteria are met.

  • Debris removal & cleanup: The reasonable cost to remove flood-damaged covered property and flood-borne debris.

  • Temporary measures: Reasonable, necessary steps to protect the property from further damage (e.g., tarps, safe dry-out). Keep all receipts.


Important limits to know (NFIP): Maximum residential building coverage is typically $250,000 and contents $100,000 under the National Flood Insurance Program; some owners purchase excess/private flood to go higher.

The Claims Process: What To Do (Step-by-Step)

  1. Report your loss immediately. Contact your insurer/agent to open a claim; you’ll be assigned an adjuster.

  2. Document everything. Before cleanup, photograph/video all rooms, water lines, and damaged items; keep a room-by-room inventory with model/serial numbers when possible. Save all receipts.

  3. Start safe cleanup. Remove standing water, ventilate and dry, and dispose of hazardous debris while keeping samples of materials when advised. Debris removal of covered property is generally insurable—retain invoices.

  4. Meet the adjuster. Walk through damage; provide your documentation. Ask about building vs. contents coverage and any potential ICC eligibility.

  5. Submit Proof of Loss if required. Follow your insurer’s instructions for forms, deadlines, and supplemental claims if hidden damage is later discovered.

  6. Coordinate permits & code compliance. If your community declares substantial damage, speak with the local floodplain administrator about ICC steps before rebuilding.


Smart Ways to Use Your Policy When Rebuilding

  • Prioritize health & safety: Electrical systems, HVAC, and contaminated materials often need replacement first to avoid hazards and mold growth.

  • Mitigate during repairs: If eligible for ICC, elevate utilities and living areas, use flood-resistant materials, and consider relocating critical systems above projected flood levels.

  • Track code-driven costs separately: ICC is earmarked for compliance measures; keeping separate estimates/invoices can speed reimbursement.

  • Prevent contractor fraud: Get multiple written bids, verify licensing, avoid large upfront payments, and be cautious of unsolicited offers. (Unfortunately, post-disaster scams are common.)


Timing Myths & Realities (So You’re Secure Next Time)

There’s usually a 30-day waiting period before a new NFIP policy takes effect—don’t wait for a storm to buy coverage. There are specific exceptions (e.g., certain loan transactions, post-wildfire flooding on federal land, and others). Ask your agent which apply to you.


Quick Checklist: Documents & Details to Save

  • Policy number and insurer contact
  • Photos/videos (wide and close-ups), dated
  • Itemized list of damaged contents with values
  • Receipts for: pumps, fans/dehumidifiers, tarps, debris removal, protective materials, temporary lodging
  • Contractor estimates and permits (keep ICC-related costs distinct) agents.floodsmart.govFloodsmart


FAQs

Does flood insurance cover temporary housing?

NFIP policies do not include Additional Living Expense (ALE) coverage; check whether your homeowners policy or disaster assistance may help. (Coverage varies; verify with your carrier.)


Can I get more than $250,000 for the building?

NFIP limits for a single-family dwelling are typically $250,000 (building) and $100,000 (contents). Some insurers offer excess/private flood to extend limits.


What if my HOA/condo building floods?

 Unit owners may need their own contents/walls-in coverage; the association’s master policy does not automatically cover your belongings or interior finishes. Review both policies to avoid gaps.


Bottom Line

Flood insurance is the most reliable way to fund recovery after a major flood. It pays for structural repairs, covered contents, cleanup, and—when required—code-compliant mitigation through ICC (up to $30,000) so you can rebuild stronger. The key is acting fast, documenting thoroughly, and coordinating early with your insurer, contractor, and local officials.


At Alcock Insurance, we are committed to offering our clients a wide range of comprehensive and affordable insurance policies. We go above and beyond to ensure that we meet your unique needs with tailored solutions. To find out more about how we can assist you, please reach out to our agency at (252) 353-1700 or 
CLICK HERE to request a free, no-obligation quote.


Disclaimer: The content provided in this blog is for informational purposes only and should not be considered professional advice. For personalized guidance, it is important to consult with a qualified insurance agent or professional. They can offer expert advice tailored to your individual situation and help you make well-informed decisions about your insurance coverage.


September 24, 2026
Businesses often classify employees as full-time or part-time for scheduling and benefits purposes, but workers’ compensation does not necessarily follow the same distinctions. For employers and employees in Greenville, NC, understanding how work status affects coverage, benefits, payroll, and claim handling can help p
September 24, 2026
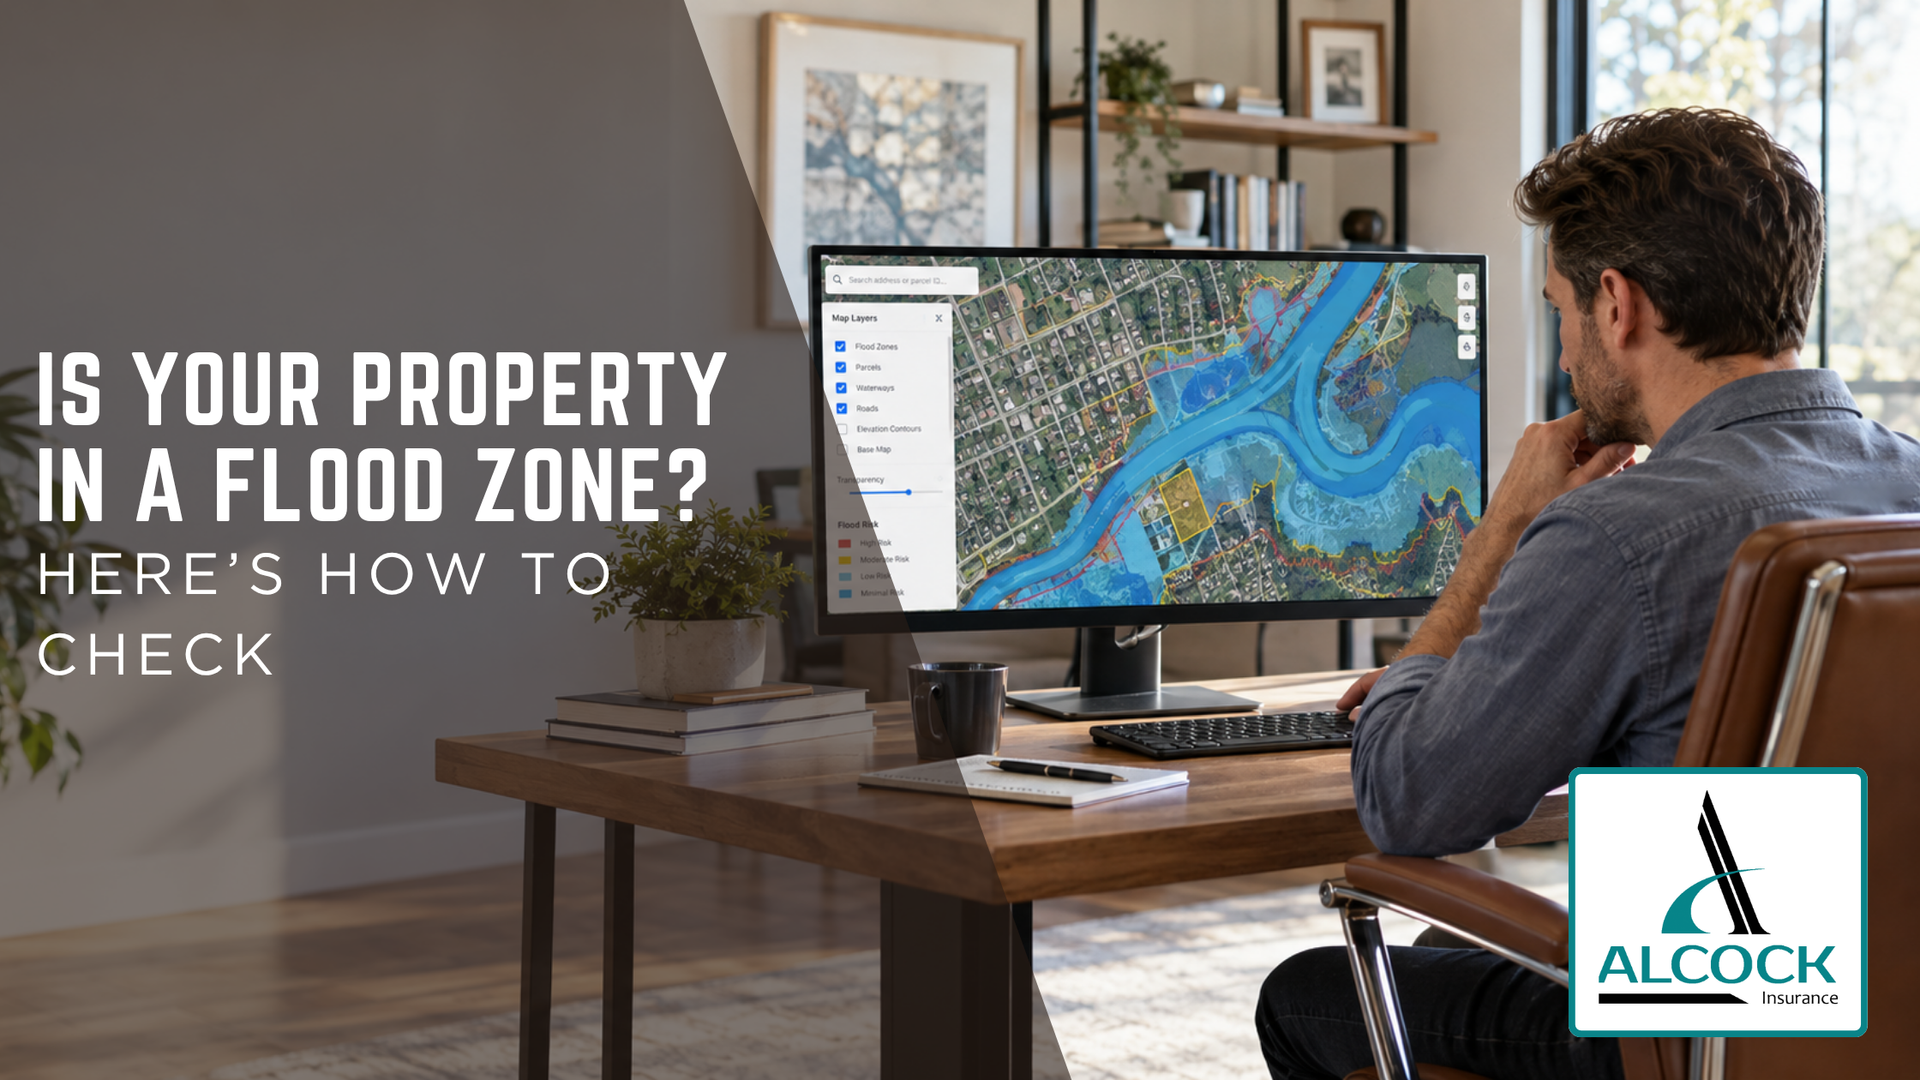
Flood risk is not always obvious from looking at a property, especially when a home is miles from a major river or coastline. For homeowners in Greenville, NC, checking the official flood map can help clarify the property's designated flood zone and provide useful information when evaluating flood insurance.
September 14, 2026
Homeowners insurance can cost dramatically more in one part of the country than another, even when the homes appear similar in size and value. For homeowners in Greenville, NC, understanding the regional factors behind insurance pricing can make it easier to evaluate premiums and identify which parts of the cost are ti
September 14, 2026
Collision coverage can be one of the most important parts of an auto policy after a crash, but many drivers are not completely sure when it applies or how it differs from other coverage. For drivers in Greenville, NC, understanding these distinctions can make the claims process easier and help prevent surprises after a
August 19, 2026
Restaurants and cafes face a mix of property, liability, equipment, employee, and food-related risks that can create expensive losses when coverage is incomplete. For owners in Greenville, NC, building the right insurance program means understanding how each policy responds to the realities of serving customers, prepar
August 17, 2026
Workers’ compensation and health insurance can both help with medical expenses, but they are designed for very different situations. For employers and employees in Greenville, NC, understanding where one type of coverage ends and the other begins can help reduce confusion after a workplace injury or illness.
August 10, 2026
Flood damage can affect much more than the main house, especially when a property includes a detached garage, storage shed, workshop, or other secondary structure. For homeowners in Greenville, NC, understanding how flood insurance treats these buildings can help prevent assumptions about coverage that may only become
August 3, 2026
Business insurance can be easy to misunderstand because many coverage assumptions sound logical until a claim actually happens. For owners in Greenville, NC, separating common myths from policy realities can help prevent gaps, improve purchasing decisions, and make coverage easier to manage as the business grows.
July 26, 2026
Flood damage can affect a home’s structure and everything stored inside it, yet those losses are not automatically insured under one shared limit. For property owners in Greenville, NC, understanding how building and contents coverage work separately can prevent major gaps when rising water damages both the home and pe
July 26, 2026
A customer injury, damaged client property, or advertising dispute can create legal expenses before a business knows whether it is responsible. For companies in Greenville, NC, commercial general liability insurance can provide an important financial defense against several common third-party claims, but its protection
Show More