What Exactly Is Flood Insurance And Who Needs It?
September 24, 2025

Flooding is one of the most common and costly natural disasters in the United States, causing billions of dollars in damage every year. Yet, many homeowners are surprised to learn that standard home insurance policies do not cover flood damage. That’s where flood insurance comes in.

If you’re wondering what flood insurance actually covers—and whether you need it—here’s a breakdown.


What Is Flood Insurance?

Flood insurance is a specialized policy that provides financial protection against damage caused by flooding. It is typically offered through the National Flood Insurance Program (NFIP), backed by the Federal Emergency Management Agency (FEMA), as well as private insurers.

What It Covers:

1.Building Coverage

  • Structure of your home (foundation, walls, plumbing, and electrical systems).
  • Permanently installed features like water heaters, central air systems, and built-in appliances.
  • Coverage limit: Up to $250,000 for residential properties under NFIP.


2. Contents Coverage

  • Personal belongings (furniture, clothing, electronics, and certain appliances).
  • Valuables like artwork and jewelry (with sub-limits).
  • Coverage limit: Up to $100,000 for residential contents under NFIP.


Who Needs Flood Insurance?

1.Homeowners in High-Risk Flood Zones

  • If you live in a Special Flood Hazard Area (SFHA), flood insurance is often required by lenders when you take out a federally backed mortgage.
  • These areas are more likely to experience flooding due to their proximity to rivers, lakes, or coastal zones.


2. Homeowners in Moderate- or Low-Risk Areas

  • FEMA estimates that over 20% of flood claims come from properties outside high-risk zones.
  • Even if not required, it can be a smart investment for peace of mind.


3. Renters

  • Renters can purchase contents-only flood insurance to protect personal belongings.
  • The landlord’s policy typically covers only the building, not tenants’ possessions.


4. Businesses

  • Commercial flood insurance is available to protect business property, equipment, and inventory.


5. Property Owners Who’ve Received Federal Disaster Aid

  • If you’ve previously received disaster relief for flood damage, you may be required to maintain flood insurance to qualify for future federal assistance.


What Flood Insurance Doesn’t Cover

  • Temporary housing or additional living expenses (unless provided by private policies).
  • Landscaping, decks, patios, fences, or swimming pools.
  • Cars or other vehicles (covered under auto insurance with comprehensive coverage).
  • Damage caused by sewer backups (unless directly caused by flooding).


Why Flood Insurance Matters

  • Financial Protection: Just one inch of water in a home can cause over $25,000 in damage.
  • Limited Federal Aid: Disaster assistance is often a loan, not free aid. Flood insurance provides direct compensation.
  • Peace of Mind: It ensures you can rebuild and replace belongings without draining your savings.


Conclusion

Flood insurance is more than just a safeguard—it’s a necessity for those in high-risk flood zones and a wise choice for many others. Since standard homeowners insurance does not cover flood damage, securing flood insurance helps protect both your home and your financial future.

The takeaway: Even if you’re not required to have it, flood insurance offers invaluable protection against one of nature’s most unpredictable and devastating forces.


At Alcock Insurance, we are committed to offering our clients a wide range of comprehensive and affordable insurance policies. We go above and beyond to ensure that we meet your unique needs with tailored solutions. To find out more about how we can assist you, please reach out to our agency at (252) 353-1700 or 
CLICK HERE to request a free, no-obligation quote.


Disclaimer: The content provided in this blog is for informational purposes only and should not be considered professional advice. For personalized guidance, it is important to consult with a qualified insurance agent or professional. They can offer expert advice tailored to your individual situation and help you make well-informed decisions about your insurance coverage.


September 24, 2026
Businesses often classify employees as full-time or part-time for scheduling and benefits purposes, but workers’ compensation does not necessarily follow the same distinctions. For employers and employees in Greenville, NC, understanding how work status affects coverage, benefits, payroll, and claim handling can help p
September 24, 2026
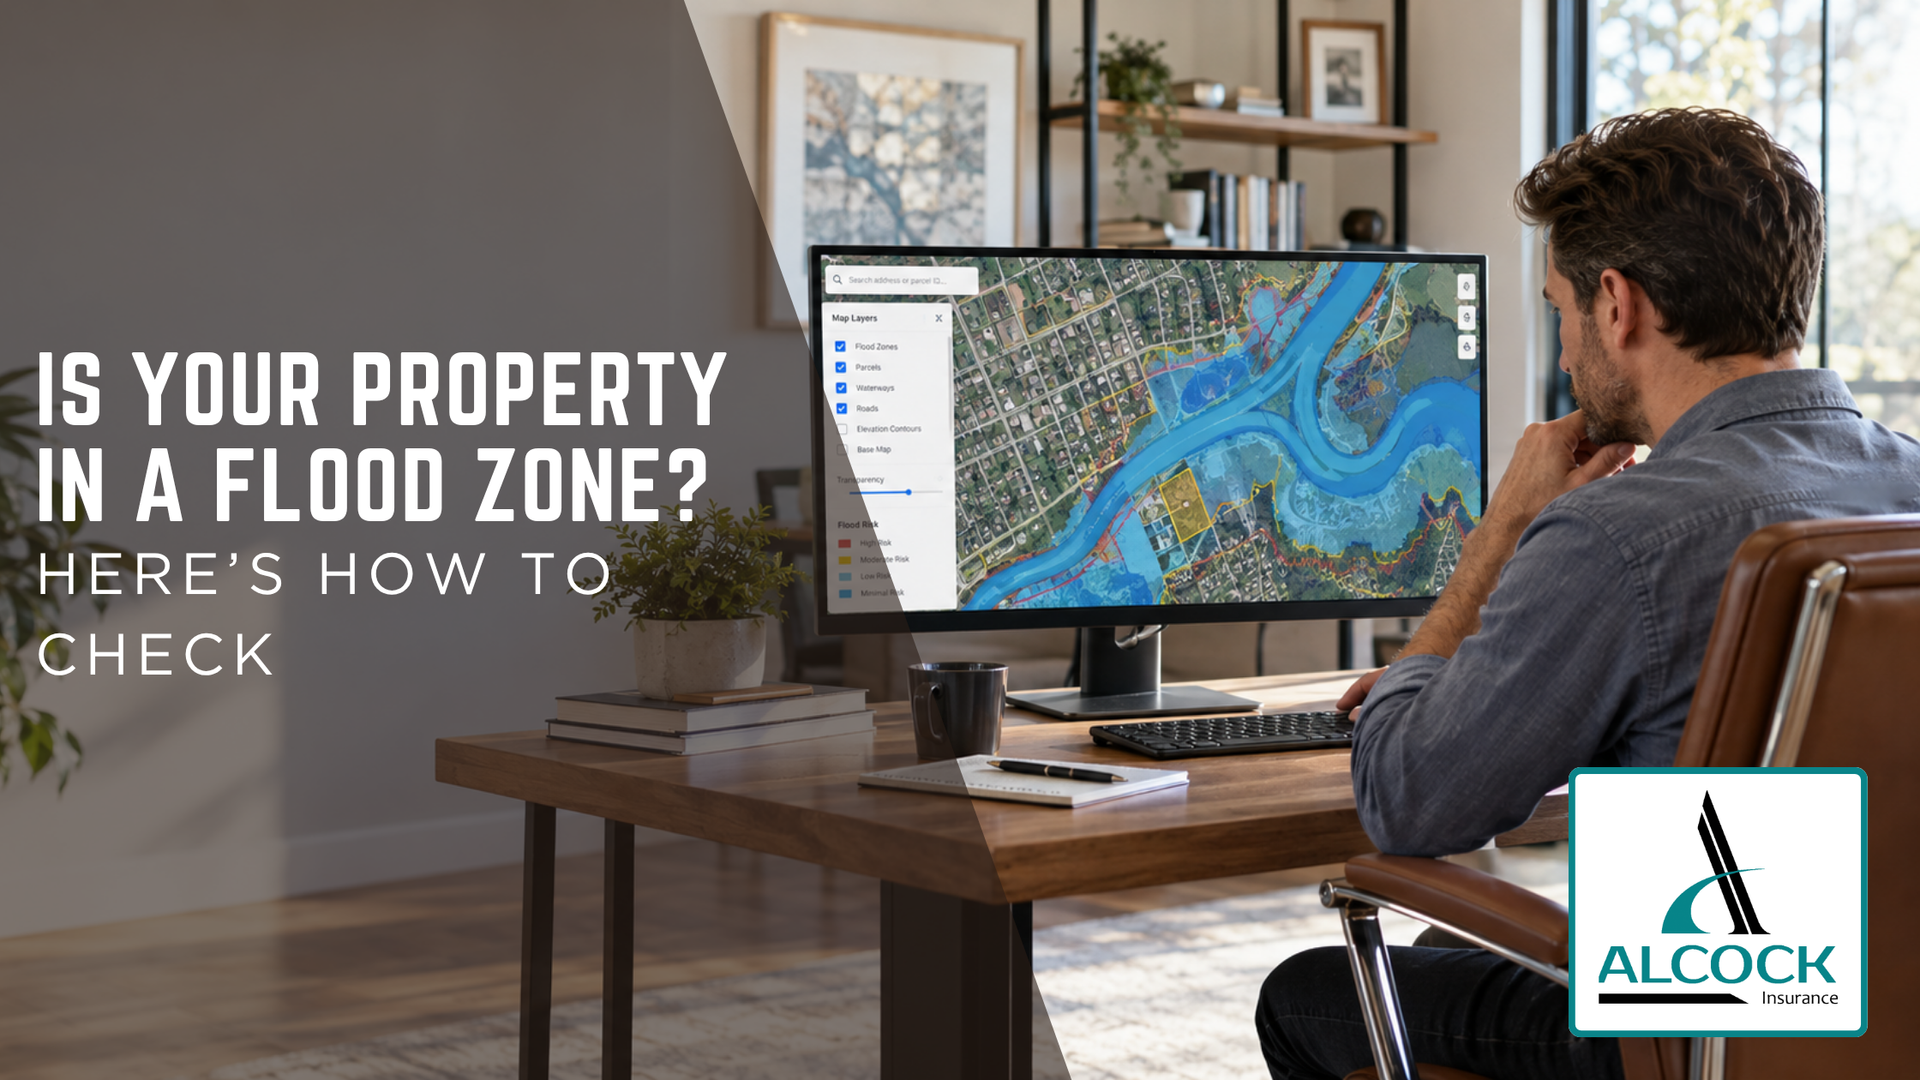
Flood risk is not always obvious from looking at a property, especially when a home is miles from a major river or coastline. For homeowners in Greenville, NC, checking the official flood map can help clarify the property's designated flood zone and provide useful information when evaluating flood insurance.
September 14, 2026
Homeowners insurance can cost dramatically more in one part of the country than another, even when the homes appear similar in size and value. For homeowners in Greenville, NC, understanding the regional factors behind insurance pricing can make it easier to evaluate premiums and identify which parts of the cost are ti
September 14, 2026
Collision coverage can be one of the most important parts of an auto policy after a crash, but many drivers are not completely sure when it applies or how it differs from other coverage. For drivers in Greenville, NC, understanding these distinctions can make the claims process easier and help prevent surprises after a
August 19, 2026
Restaurants and cafes face a mix of property, liability, equipment, employee, and food-related risks that can create expensive losses when coverage is incomplete. For owners in Greenville, NC, building the right insurance program means understanding how each policy responds to the realities of serving customers, prepar
August 17, 2026
Workers’ compensation and health insurance can both help with medical expenses, but they are designed for very different situations. For employers and employees in Greenville, NC, understanding where one type of coverage ends and the other begins can help reduce confusion after a workplace injury or illness.
August 10, 2026
Flood damage can affect much more than the main house, especially when a property includes a detached garage, storage shed, workshop, or other secondary structure. For homeowners in Greenville, NC, understanding how flood insurance treats these buildings can help prevent assumptions about coverage that may only become
August 3, 2026
Business insurance can be easy to misunderstand because many coverage assumptions sound logical until a claim actually happens. For owners in Greenville, NC, separating common myths from policy realities can help prevent gaps, improve purchasing decisions, and make coverage easier to manage as the business grows.
July 26, 2026
Flood damage can affect a home’s structure and everything stored inside it, yet those losses are not automatically insured under one shared limit. For property owners in Greenville, NC, understanding how building and contents coverage work separately can prevent major gaps when rising water damages both the home and pe
July 26, 2026
A customer injury, damaged client property, or advertising dispute can create legal expenses before a business knows whether it is responsible. For companies in Greenville, NC, commercial general liability insurance can provide an important financial defense against several common third-party claims, but its protection
Show More